The National Backdrop
Nationally, demand strengthened through the middle of 2026. Cushman & Wakefield reported U.S. industrial net absorption of 76.6 million square feet in the third quarter, the highest quarterly total since early 2023 and the second quarter in a row above 70 million, bringing the year to 203 million square feet. National vacancy held at (6.8%), 20 basis points below its late-2025 peak, and the average asking rent reached ($10.40) per square foot, up (4.0%) from a year earlier, with warehouse and distribution space at ($10.06).
New supply stayed modest at about 64 million square feet in the third quarter, but developers are building again. The national construction pipeline grew (23%) from a year earlier to 324.7 million square feet. In the Northeast, vacancy eased from (7.7%) in the second quarter to (7.5%) in the third. Outside Texas, Cushman & Wakefield named the Pennsylvania I-81 and I-78 corridor as one of five inland markets with more than 5 million square feet of completions so far this year.
Northeastern Pennsylvania, Quarter by Quarter
Cushman & Wakefield tracks Northeastern Pennsylvania as one of the submarkets in its Pennsylvania distribution corridor report, about 89.4 million square feet of industrial space at the end of September. After a first half defined by new supply, the third quarter was about leasing. Vacancy eased from (7.1%) at the end of June to (6.9%) at the end of September, and the submarket absorbed 383,600 square feet in the third quarter. Year-to-date net absorption reached 521,915 square feet. That is more than the quarterly figures published earlier in the year add up to, which implies the first half was revised upward, though Cushman & Wakefield does not break out the revision.
The change in Cushman & Wakefield's year-to-date completions implies only about 263,500 square feet delivered in NEPA during the third quarter, against 383,600 square feet of net absorption, which is why vacancy fell. The bigger change was what started. Space under construction rose from about 2.3 million square feet at the end of June to 5.5 million at the end of September, the largest pipeline of any submarket in the corridor. Tenants leased just over 2.0 million square feet in NEPA through the first nine months of the year.
| NEPA Measure | Q2 2026 | Q3 2026 |
|---|---|---|
| Vacancy | 7.1% | 6.9% |
| Net Absorption, Quarter | +1,139,069 SF | +383,600 SF |
| Net Absorption, Year to Date | +86,128 SF | +521,915 SF |
| Under Construction | 2.29M SF | 5.53M SF |
| Completions, Year to Date | 2,338,123 SF | 2,601,623 SF |
| Warehouse Asking Rent | $7.79 / SF | $7.81 / SF |
| Inventory | 89.2M SF | 89.4M SF |
The second-quarter column is as Cushman & Wakefield published it in its second-quarter report, when those figures were marked preliminary. The two year-to-date absorption figures do not differ by exactly the third-quarter total because the earlier quarters appear to have been revised since.
How NEPA Compares Along the Corridor
Beginning with the third quarter, Cushman & Wakefield reports the corridor as five submarkets rather than three, adding the Split and the I-81 South corridor alongside Northeastern Pennsylvania, the Lehigh Valley and Central Pennsylvania. The corridor as a whole now covers about 468.6 million square feet.
| Submarket | Vacancy, Q3 2026 | Net Absorption, Q3 2026 | Warehouse Asking Rent |
|---|---|---|---|
| Northeastern PA | 6.9% | +383,600 SF | $7.81 / SF |
| Lehigh Valley | 7.7% | +953,141 SF | $11.97 / SF |
| Central PA | 7.9% | +1,020,639 SF | $8.84 / SF |
| Split | 10.4% | -2,110,417 SF | $8.23 / SF |
| I-81 South | 9.5% | -559,212 SF | $7.43 / SF |
| Corridor Total | 8.2% | -312,249 SF | $9.07 / SF |
NEPA finished the quarter with the lowest vacancy of the five submarkets, at (6.9%) against (8.2%) for the corridor. Corridor vacancy rose 60 basis points in the quarter, largely because of space vacated in the Split by consumer electronics and automotive tenants, while vacancy fell in both the Lehigh Valley and Northeastern Pennsylvania. Corridor leasing reached 15.9 million square feet through September, already (12.8%) more than in all of 2025.
Lee & Associates of Eastern Pennsylvania, which draws the region on its own boundaries, reported that across its six-submarket territory from Central Pennsylvania to Delaware vacancy rose 21 basis points to (8.39%) in the third quarter as 11 buildings delivered, nearly (80%) of their space vacant, while net absorption stayed positive at 3.6 million square feet and leasing reached 12.4 million square feet. Lee noted that vacant speculative deliveries and tenant givebacks affected the Lehigh Valley and Northeastern Pennsylvania. Lee's release gives no NEPA figures and the two firms draw their regions differently, so their descriptions of the quarter are not directly comparable.
The Cost Advantage
The case for Pittston and the broader NEPA submarket is still cost. Comparing warehouse space with warehouse space in the third quarter of 2026, Cushman & Wakefield put asking rent at ($7.81) per square foot in NEPA, ($12.97) in Philadelphia and ($17.43) in Northern New Jersey. On a 200,000 square foot building, the gap to Northern New Jersey is about ($1.9 million) a year in rent, and the gap to Philadelphia is about ($1.0 million). Cushman & Wakefield reported that e-commerce, logistics and food and beverage users drove the corridor's largest leases in the quarter, and a rent gap of that size is a large part of what draws them up the I-81 and I-78 corridors.
Workforce
Luzerne County's unemployment rate was (5.2%) in August 2026, against a national rate of (4.3%), both before seasonal adjustment. August is the latest month for which the county figure has been published. Across the distribution corridor as a whole, Cushman & Wakefield reported employment up (0.5%) from a year earlier in the third quarter, with manufacturing accounting for (12.4%) of jobs, 280 basis points above its national share.
Activity During the Period
| Company | Location | Detail | Date |
|---|---|---|---|
| Premier Brands of America | 45 Commerce Drive, Scott Twp. (Lackawanna Co.) | $15M Plant, 58 Jobs Over Three Years | Apr 2026 |
| FedEx (Federal Express Corporation) | 1000 Sathers Drive, Pittston | Facility Closure, 63 Employees Affected | May 2026 |
| Forbo Flooring | 18 Maplewood Drive, Humboldt Industrial Park, Hazleton | Flotex Plant Opened, About 90 Employees | May 2026 |
| Mericle Commercial Real Estate Services | CrossRoads East, Hazle Twp. | Seven Speculative Buildings Under Development, 147,000 to 450,000 SF Each, 2M+ SF Combined | Jul 2026 |
| NorthPoint Development | Hazleton Logistics 141, Building Five, Hazleton | Groundbreaking, Just Over 1M SF, Completion Expected July 2027 | Jul 2026 |
| Nucor Towers & Structures | Valmont Industrial Park, West Hazleton | Expansion Celebrated, Nearly $60M and 76,000+ SF Added Since 2022 | Jul 2026 |
| TAH Developers | 4555 Oldfield Boulevard, Pittston | 263,500 SF Multi-Tenant Building Completed, Suites of 62,000 to 108,500 SF | Aug 2026 |
The two largest projects announced during the period are both around Hazleton. Mericle's first phase at CrossRoads East, a 1,516-acre park planned for 13.8 million square feet across four phases, is scheduled to deliver from the third quarter of 2026 into the second quarter of 2027. NorthPoint broke ground on its fifth building at Hazleton Logistics 141, a park planned for six buildings and 5.3 million square feet, whose first building of 1.05 million square feet is occupied by RJW Logistics Group. Those two projects alone account for roughly 3 million square feet of construction, though Cushman & Wakefield's report does not list the projects it counts.
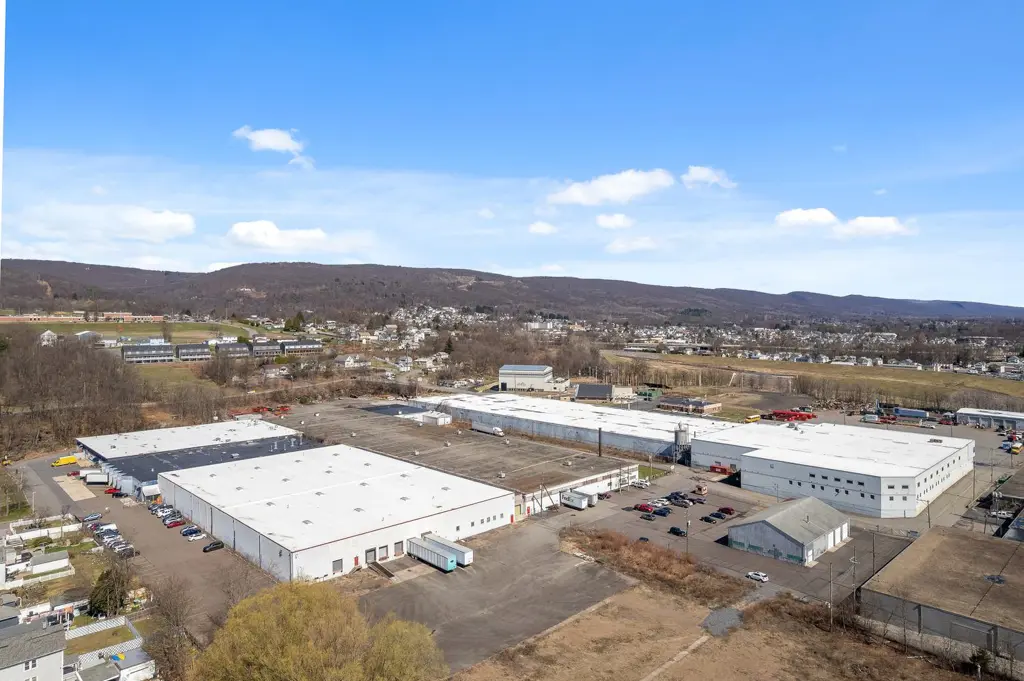
Closer to Pittston, TAH Developers' Class A concrete tilt-wall building on Oldfield Boulevard received its certificate of occupancy with three suites available, 36-foot clear heights and 42 dock-high doors. Its 263,500 square feet are the same as the third-quarter NEPA completions implied by Cushman & Wakefield's year-to-date figures, though the report does not name the buildings it counts. FedEx closed its facility on Sathers Drive in Pittston in May, affecting 63 employees according to the notice filed with the Pennsylvania Department of Labor and Industry.
Cushman & Wakefield's key sales table for the third quarter listed no Northeastern Pennsylvania building sales, as in the first half. Most Class A product here is built and held long term by private developers rather than traded, so the submarket does not produce a comp set deep enough to publish a reliable price per square foot or cap rate for the period.
Outlook
Cushman & Wakefield expects corridor fundamentals to stay resilient, with further occupancy gains in the fourth quarter, and noted that occupiers had already committed to (52.5%) of the space delivered this year through build-to-suit construction or preleasing. Lee & Associates expects about 10 million square feet of new construction to deliver across its region over the next six months. For NEPA the question for 2027 is how quickly the 5.5 million square feet now under construction is leased as it delivers.
Methodology and Sources
This report compiles published industry, government and trade press sources rather than a single proprietary database, and every figure is reported for, or as of the end of, the April through September 2026 period, with year-to-date figures covering January through September and park totals and forecasts named as such. Every transaction listed was announced or took effect in the period. Submarket vacancy, absorption, completions, construction, leasing and rent figures come from Cushman & Wakefield's Pennsylvania I-81, I-78 and I-81 South industrial MarketBeat for the third quarter of 2026, with second-quarter figures as published in its second-quarter report, which were marked preliminary. Regional figures and the qualitative NEPA finding come from Lee & Associates of Eastern Pennsylvania, whose boundaries differ from Cushman & Wakefield's. National, Philadelphia and Northern New Jersey benchmarks come from Cushman & Wakefield's U.S. Industrial MarketBeat. The rent gap on a 200,000 square foot building is the difference in asking rent per square foot multiplied by 200,000. Transaction detail comes from developer, government and economic development announcements, local press and the state's WARN notices. A county ranking of top employers was left out because the most recent edition ranks the first quarter of 2026, which falls outside this period.
- Cushman & Wakefield, PA I-81 / I-78 / I-81S Industrial MarketBeat, Q3 2026, and PA I-81 / I-78 Industrial MarketBeat, Q2 2026 (preliminary)
- Cushman & Wakefield, U.S. Industrial MarketBeat, Q3 2026
- Lee & Associates of Eastern Pennsylvania, Q3 2026 Industrial Market Report release (October 14, 2026)
- U.S. Bureau of Labor Statistics, Local Area Unemployment Statistics for Luzerne County and the national unemployment rate, not seasonally adjusted, August 2026, via FRED
- Office of the Governor of Pennsylvania, Premier Brands of America announcement (April 8, 2026)
- Pennsylvania Department of Labor and Industry, WARN notices, Federal Express Corporation, Pittston (effective May 2, 2026)
- Standard-Speaker, Forbo Flooring grand opening (May 7, 2026)
- Mericle Commercial Real Estate Services, CrossRoads East announcement (July 16, 2026)
- Times Leader, NorthPoint Development Hazleton Logistics 141 Building Five groundbreaking (July 22, 2026)
- CAN DO, Inc., Nucor Towers & Structures expansion celebration (July 24, 2026)
- Penn's Northeast, TAH Developers completes Class A industrial building in Pittston (August 4, 2026)
Talk to a Local Broker Who Knows This Market
Jonathan J. Nelson Real Estate works the Greater Pittston and NEPA market every day, handling residential and commercial sales, as well as investment guidance and property management. If you are buying, selling, or investing, let's talk.
Contact Jonathan J. Nelson Real Estate