If your home is appraised for a conventional mortgage after November 1, the report the appraiser delivers will look nothing like the one lenders have used for most of the last twenty years. Fannie Mae and Freddie Mac are replacing the familiar Uniform Residential Appraisal Report, the form known as the 1004, and the family of forms around it with one data-driven report built on a new data standard called UAD 3.6.
The value an appraiser reaches will still come from the same place, which is the home, its condition and recent comparable sales. What changes is how much the report records, how it is measured and photographed, and how little room is left for shortcuts. For sellers that means preparation matters more. For buyers it means a more detailed report, and possibly a few more days in the contract timeline during the changeover.
The Dates That Matter
| Date | What Happens |
|---|---|
| September 8, 2025 | Limited Production Begins for a Small Group of Lenders |
| January 26, 2026 | Any Lender May Use the New Report, Old Format Still Accepted |
| August 6, 2026 | Delivery Portal Warns on Old-Format Submissions |
| November 2, 2026 | New Report Mandatory for Every New Fannie Mae and Freddie Mac Appraisal |
| May 3, 2027 | Old Format Retired, Including Revisions to Pre-November 2 Reports |
Until November 2 the old format is still accepted, and from August 6 the portal lenders use to deliver appraisals to Fannie Mae and Freddie Mac has been warning when it receives one. The trigger is the date the lender first submits the appraisal to that portal, not the date the appraiser inspects the house. An old-format report submitted on or after November 2 is rejected, and after May 3, 2027 the old format is not accepted even for revisions. If you are under contract now and the appraisal is ordered for late October, ask the lender which format they are using.
One Report Instead of Many
Today an appraiser picks a form by property type. The 1004 covers a single-family home, the 1073 a condominium, the 1025 a two to four unit building, the 2055 an exterior-only appraisal, and there are separate forms for manufactured homes, updates and completions. Freddie Mac lists more than a dozen forms being retired, including the 1004, 1073, 1075, 2055, 1004C, 1025, 2090, 2095 and 1004D.
They are replaced by one report that changes shape based on the property. A duplex, a condo and a farmhouse on acreage all use the same report, which expands to include the sections that apply. The report also supports traditional, hybrid, desktop and exterior-only assignments. Form numbers go away entirely. In Freddie Mac's words, the data that describes the property now drives the report.
The first page is new as well. It is a summary with the appraised value and a photo of the home, and photos now sit inside the section they document instead of at the back.
What the Appraiser Records Now
The condition and quality ratings that run from C1 to C6 and Q1 to Q6 keep their scale, but the definitions were rewritten and the home now receives separate ratings for the interior and the exterior. Kitchens and bathrooms each get their own record of whether and when they were updated and what condition they are in.
The report also captures details the old form had no place for. Among them are the estimated age of the roof, ceiling heights, converted areas, whether the furnace sits below grade, broadband availability, solar panels and whether they are owned or leased, green certifications and energy ratings, and disaster mitigation such as flood vents or storm shutters. An accessory dwelling unit gets its own section with its own measurements. Defects and deficiencies are recorded individually, with where they are, whether they affect soundness, and what repair is recommended.
Square Footage Is Measured One Way
Fannie Mae has required appraisers to measure to the ANSI Z765 standard since April 2022, but appraisers could note an exception and depart from it. Under the new report that exception is gone. Above-grade living area and below-grade space are reported separately, and a finished area generally needs a seven-foot ceiling to count.
This matters to sellers because the square footage in the MLS and in the county assessment record was usually not measured to ANSI. Fannie Mae says so directly. A finished basement, a room with a sloped ceiling or a converted porch can all come out differently in the appraisal than on the listing. When the appraiser's number is smaller than the listing, buyers notice.
Photographs of Every Room That Matters
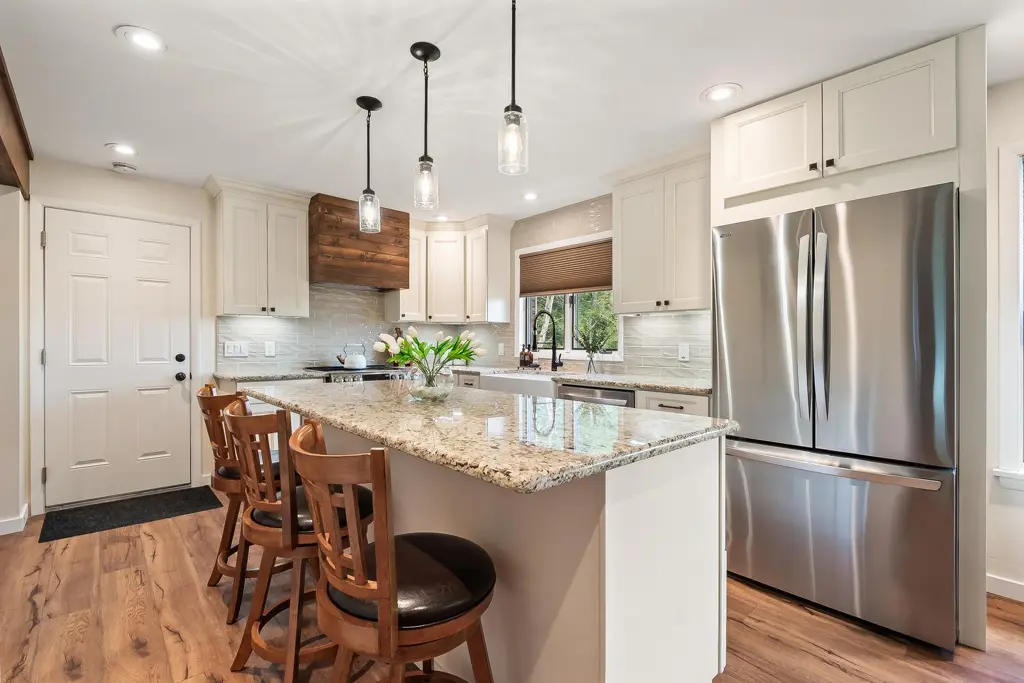
The photo requirements are now specific. Every appraisal must include the front of the home, a street scene, every kitchen, every bathroom and the main living areas, which the GSEs define to include the living room, family room, dining room and all bedrooms. Where they exist, the appraiser must also photograph finished and unfinished basements, recent renovations, an accessory unit, outbuildings and any view that affects value.
What Sellers Should Do
- Have the home measured to ANSI Z765 before listing, and list the square footage you can defend. It is cheaper to find a gap before the appraiser does.
- Assume every room will be photographed. Bedrooms, bathrooms and the basement should be accessible and ready, not used as storage for the showing.
- Write down what has been updated and when. Kitchen and bath renovations, the roof, heating and cooling, windows and additions all map to specific fields now, and a dated list with materials helps the appraiser record them correctly.
- If you have solar, know whether the panels are owned or leased and have the paperwork. The report records it.
- Note mitigation features such as a sump system, flood vents, a generator or impact-rated windows. There is now a place for them.
What Buyers Should Do
- Ask your lender early whether the appraisal will be in the new format, especially for a contract that straddles November 2.
- Build a little more time into the appraisal and financing contingency dates during the changeover. Inspections under the new report record more, and lenders and appraisers are still adjusting.
- Read the report. The new summary page, room-by-room photos and itemized deficiencies give you more information about the house than the old form did.
- If you believe the value is wrong, a borrower on a Fannie Mae or Freddie Mac loan may request one reconsideration of value per appraisal and may submit up to five alternative comparable sales.
FHA, VA and USDA Loans
The redesign was built by Fannie Mae and Freddie Mac, and the November 2 date applies to loans sold to them. The new data standard was designed to carry FHA, VA and USDA requirements too, but each agency sets its own schedule. FHA announced in June 2026 that it will adopt the new format and that it will announce the optional start date and a later mandatory date separately. VA and USDA had not published a timeline when this was written. Until they do, government-backed loans may continue on the current forms.
What Has Not Changed
An appraisal is still an opinion of market value by a licensed or certified appraiser, based on the property and comparable sales. The appraiser still works for the lender, not the buyer or seller. The 2024 edition of the Uniform Standards of Professional Appraisal Practice, which added an explicit nondiscrimination section to the appraiser ethics rule, remains in effect. In Pennsylvania, appraisers must also complete a seven-hour valuation bias and fair housing course, which became a required part of qualifying and continuing education on January 1, 2026.
Some loans will not need an appraisal at all. Fannie Mae's value acceptance and Freddie Mac's equivalent can waive the appraisal on eligible loans, and a newer option pairs the waiver with an on-site property data collection, including photos and an ANSI floor plan, by a trained collector who does not have to be an appraiser.
Sources
- Freddie Mac, UAD and Forms Redesign FAQs, and UAD Redesign Timeline fact sheet
- Freddie Mac and Fannie Mae, UAD Photo and Image Job Aid (June 2026) and UAD Inspection and Reporting Tips (October 2025)
- Fannie Mae, UAD 3.6 broad production announcement (January 26, 2026), UAD 3.6 policy supplement, and ANSI measurement FAQ
- Fannie Mae Selling Guide B4-1.4-10 Value Acceptance and B4-1.4-11 Value Acceptance + Property Data
- Fannie Mae, Reconsideration of Value requirements
- U.S. Department of Housing and Urban Development, FHA INFO 2026-15 and Mortgagee Letter 2025-08
- The Appraisal Foundation, Uniform Standards of Professional Appraisal Practice, 2024 edition
- Pennsylvania State Board of Certified Real Estate Appraisers, Valuation Bias and Fair Housing education announcement
- Pennsylvania Association of REALTORS, Top Things for REALTORS to Know About Upcoming Appraisal Changes (September 2026)
- National Association of REALTORS, Appraisals Will Look Very Different in the Near Future (May 2025)
Talk to a Local Broker Who Knows This Market
Jonathan J. Nelson Real Estate works the Greater Pittston and NEPA market every day, residential, commercial, industrial, and land. If you are buying, selling, or investing, let's talk.
Contact Jonathan J. Nelson Real Estate